
Tax Alert - Reminder of changes to Vacant Residential Land Tax rules in Victoria from 1 January 2025

Lowe Lippmann Chartered Accountants

Reminder of changes to Vacant Residential Land Tax rules in Victoria from 1 January 2025


Background


Vacant residential land tax (VRLT) may apply to residential land that is vacant for more than 6 months in the preceding calendar year (ie. from 1 January 2024 to 31 December 2024). Residential land can include:

  • land with a home on it;
  • land with a home which is being renovated or where a former home has been demolished and a new home is being constructed; or
  • land with a home on it that has been uninhabitable for 2 years or more.


Residential land does not include land without a home on it (sometimes called unimproved land), commercial residential premises, residential care facilities, supported residential services or retirement villages.


The scope of what types of residential property will be exposed to the VRLT rules is being expanded over time, as follows:
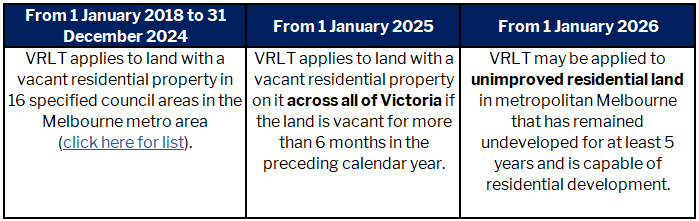
The State Revenue Office (SRO) will release more information about unimproved land and VRLT in the short term.


The 6 month period of vacancy does not need to be continuous to trigger the VRLT rules.


VRLT rates & timing


For the year ending 31 December 2024, the VRLT rate is 1.0% of the capital improved value (CIV) of taxable land, which is the value of the land, buildings and any other capital improvements made to the property. The CIV is displayed on the council rates notice for the property.


Unlike land tax, there is no taxable value threshold for VRLT, which means land with a vacant residential property may be liable for VRLT regardless of its CIV.


From 1 January 2025, a progressive rate of VRLT will apply to non-exempt land with a vacant residential property and the rate is based on the number of consecutive calendar years the land has been liable for VRLT, as follows:
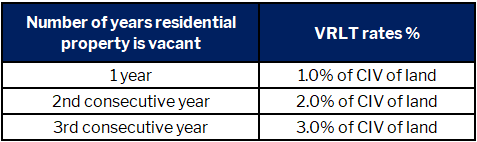
The use of the residential land in the calendar year ending 31 December 2024 will determine whether VRLT applies in 2025. For example, if land owned was vacant for more than 6 months during the calendar year ending 31 December 2024, the land owner must make a VRLT notification by 15 January 2025, and if any assessment is required it will be sent by the SRO during February 2025.


VRLT notifications


A land owner must lodge a VRLT notification via the SRO online portal (click here) by 15 January each year if:

  • residential land is vacant for more than 6 months during the calendar year;
  • the land is no longer vacant for more than 6 months during the calendar year;
  • an exemption applies (discussed below); or
  • an exemption ceases to apply/exemption changes.


If a land owner has made a VRLT notification in a previous year and circumstances have not changed, subsequent notification do not need to be made.


VRLT exemptions


If a property is exempt from land tax, it is also exempt from VRLT. In addition, there are four specific VRLT exemptions which apply to:

  1. holiday homes;
  2. apartments/homes/units used for work accommodation purposes;
  3. property transfers during the preceding year; and
  4. new residential land & newly developed properties where ownership is unchanged.


We will consider each exemption here and note any changes to the requirements from 1 January 2025.


VRLT exemption 1: Holiday homes
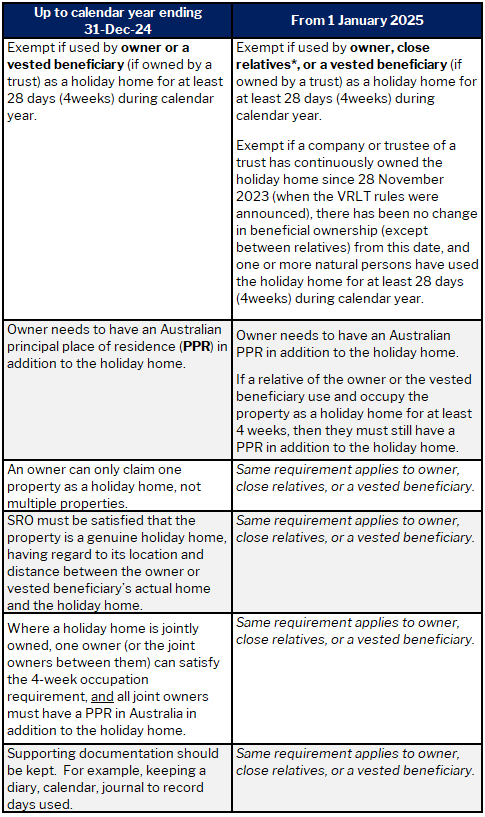
*A close relative of the owner includes a spouse or domestic partner, (grand) parents, (grand) children of owner/vested beneficiary or partner; brother, sister, niece or nephew of owner/vested beneficiary and their respective partners.


We note that use of the holiday home by friends (and not close relatives) does not count towards the 4-week occupation requirement from 1 January 2025.


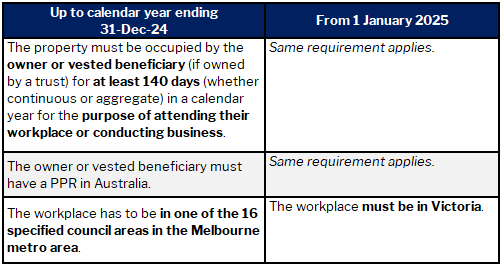
VRLT exemption 2: Work accommodation


The work accommodation exemption applies to circumstances where someone may live in regional Victoria or another state or territory and maintain an apartment/townhouse to stay in while they work away from their usual home.

VRLT exemption 3: Property transfers during the preceding year


Properties that change ownership during a calendar year are exempt from VRLT in the following year.


The change of ownership must occur during the calendar year.  It is not sufficient that the property is available for sale or awaiting settlement as at 31 December of the year preceding the tax year. Importantly settlement must take place no later than 31 December.


This exemption remains unchanged after 1 January 2025.


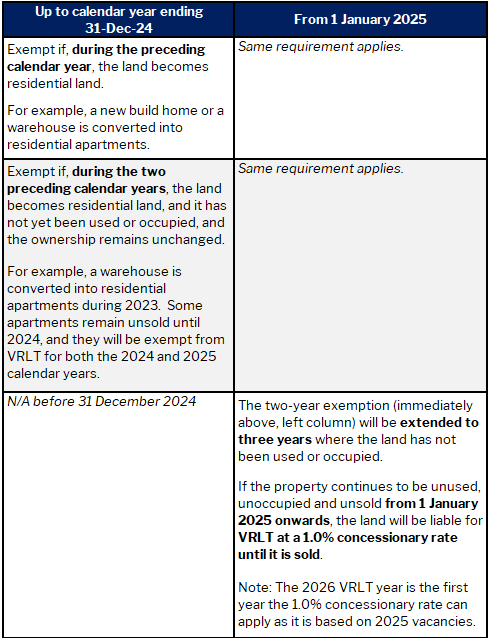
VRLT exemptions 4: New residential land & newly developed properties where ownership is unchanged


Please do not hesitate to contact your Lowe Lippmann Relationship Partner if you wish to discuss any of these matters further.

Liability limited by a scheme approved under Professional Standards Legislation


November 4, 2026
ATO to continue accepting credit cards until 30 June 2027, but the clock it still ticking Last month, in our Practice Update for October 2026 ( see here ), we noted the Australian Tax Office ( ATO ) announced it will stop accepting credit cards as a payment method after 30 November 2026, following the Reserve Bank of Australia’s ( RBA ) ban on card surcharges from 1 October 2026. The ATO has since confirmed that it will continue to accept credit card payments for tax obligations until 30 June 2027 . After 30 June 2027, taxpayers who wish to continue using a credit card to meet their tax obligations may continue to use third-party payment providers as outlined at www.ato.gov.au/howtopay What do these change mean for you? The extension does not cancel the planned withdrawal of direct credit card payments. From 1 July 2027, you will need to use another method to pay the ATO directly. Available alternatives include: Debit card BPAY Bank transfer Direct debit Payment at Australia Post (where available) International money transfer services (where applicable) Some third-party payment providers may continue to offer ways to pay tax using a credit card after the deadline. However, these services may charge additional fees and take longer to process payments. Check the total cost, processing time and payment conditions before relying on one. Why does your payment method matter? Credit cards can help bridge short-term cash-flow gaps, but the convenience comes at a cost. Interest, annual fees and other charges can erode the benefit, particularly if you regularly carry a balance. There is also a risk that a payment will not be processed in time, potentially leaving you with an overdue tax liability and additional interest. Switching to BPAY, bank transfer or direct debit may provide a simpler and more predictable way to manage tax payments. The right option will depend on your circumstances, including when funds are available in your business account and whether you need to retain flexibility over payment dates. Pay particular attention if you have an existing ATO payment plan linked to a credit card. The ATO has been contacting affected taxpayers, but you should check your own arrangements rather than assume they will continue unchanged. Confirm how future instalments will be paid and allow enough time to update the payment method before the deadline. What should you do now? Use the extended timeframe to prepare rather than leaving the change until the last minute. Review your current arrangements. Check whether you use a credit card for one-off tax payments, regular instalments or an ATO payment plan. Choose an alternative. Consider which payment method best suits your cash-flow cycle, taking account of fees and processing times. Update recurring payments early. Make sure any new arrangements are in place well before 30 June 2027 and check that payments are processed successfully. Review your cash flow. If you rely on the credit card interest-free period to manage tax liabilities, consider whether you need to set aside funds earlier or adjust your payment planning. Seek advice if needed. If tax payments are putting pressure on your cash flow, speak with us early so we can help you review your position and consider practical ways to manage upcoming liabilities. The extension to 30 June 2027 gives businesses more time to adjust, but it should not be mistaken for a permanent reprieve. Planning ahead can help you avoid unnecessary fees, missed payments and last-minute disruption when the ATO’s direct credit card facility closes.
October 7, 2026
ATO to stop accepting credit cards as payment method after 30 November 2026 The Australian Tax Office ( ATO ) has announced it will stop accepting credit cards as a payment method after 30 November 2026. The move follows after the Reserve Bank of Australia’s ( RBA ) Review of Merchant Card Payment Costs and Surcharging, where the RBA concluded that “it is in the public interest” to scrap surcharging for all designated card networks from 1 October 2026 (including EFTPOS, Mastercard, and Visa). It said that as a government agency, the ATO has decided it would not be appropriate for the cost of credit card merchant fees to be transferred to the community. The ATO recognises that some taxpayers currently rely on credit card payments to manage their tax payments and understands this change may require some adjustments. The ATO is writing directly to those who currently have a payment plan linked to a credit card to explain the changes and outlining the steps they need to take. There are alternative payment options available for taxpayers, including direct deposit, direct debit from a debit card, direct debit from an Australian cheque or savings account, Government EasyPay, in person at Australia Post, by mail, or international money remitter. The ATO said it is committed to helping taxpayers transition to alternative payment methods and will continue to support those experiencing financial hardship or other circumstances that make it difficult to meet their obligations. Alternative payment options for taxpayers are outlined at www.ato.gov.au/howtopay Taxpayers who need extra support are encouraged to visit www.ato.gov.au/supporttolodgeandpay , contact the ATO on 13 11 42 during business hours or speak with their registered tax professional.
September 4, 2026
Yesterday, Treasurer Jim Chalmers released draft legislation to implement the key components of the 30% minimum trust tax on discretionary trusts announced in the Federal Budget during May 2026.
More Posts